

Solar farms given contracts by the British government to supply electricity to the grid are paying larger and larger sums to electricity consumers. Far from being given subsidies by consumers, they are subsidising the consumers. They will also act to depress electricity prices in general.
In recent years there have been auctions held by the UK Government for contracts to supply solar PV (as well as other renewable energy technologies) to supply power to the grid. Those who bid to be paid the lowest price in £ per MWh are given contracts. The contracts last 15 years or, more recently, 20 years. The so-called ‘contracts for difference’ (CfDs) work by paying the generators the difference between the contract price they have been awarded and the wholesale power price. The wholesale power price is set by competition between power plant operators in a market organised by the National Electricity System Operator (NESO). The wholesale power price is the biggest single element of electricity consumers’ bills.
The CfDs are generally referred to as ‘subsidies’ on the expectation that the wholesale power price will have to be topped up to meet the CfD price they have been awarded. However, when wholesale power prices are high, then the opposite happens, and generators have to pay the money back to consumers because the CfD price is actually lower than the wholesale price. Recently installed solar farms have lower-priced CfDs compared to the earliest (CfD) ones that were installed. Hence solar farms are now returning money to consumers and this situation has become the norm. This is helped by the fact that since 2021, wholesale power prices have been much higher than they were previously.
You can see from Figure 1 that the ‘subsidy’ given to the earlier, more expensive, solar farms is now being replaced by negative subsidies (ie money to consumers). Energy Consultant Tom Bent prepared Figure 1 using data from the Low Carbon Contracts Company (LCCC). The LCCC runs the CfD programme on behalf of the UK Government.
This means that larger and larger amounts of money are being paid to consumers by solar farms with CfD contracts. The pattern of negative subsidies began in the summer of 2025 and is mounting up at a rapid rate. Now the CfD solar farm programme as a whole is delivering increasing sums to the consumer (net of earlier subsidies). This negative subsidy is skating past the £10 million level and is heading for very large amounts indeed as the installed fleet of solar farms greatly increases.
Figure 1
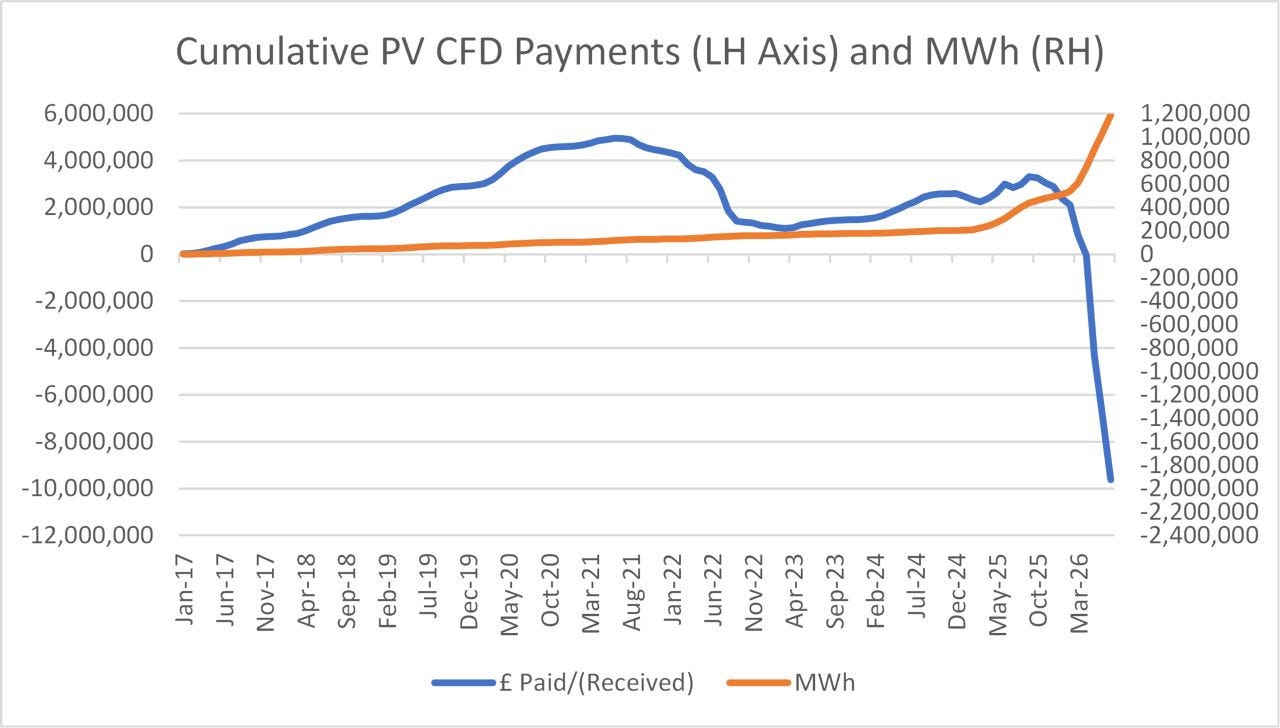
Figure 1 prepared by Tom Bent and reproduced with his kind permission; see original publication HERE
The ‘negative subsidies’ from the solar farms are paid back to the electricity suppliers. OFGEM, through the mechanism of the price cap, ensures that these gains are taken into account when deciding how much the electricity suppliers can charge domestic consumers.
Figure 2 shows how wholesale power prices (using 2024 prices as a base) have been a lot higher since 2021. These prices are determined by the European price of gas. This period covers the Ukraine War, then the replacement of Russian by other sources and, most recently the effects of the US/Israel/Iran War. (note the 2026 figure is an average of the prices up to midsummer, with prices jumping upwards from the beginning of March when the war started).
Figure 2
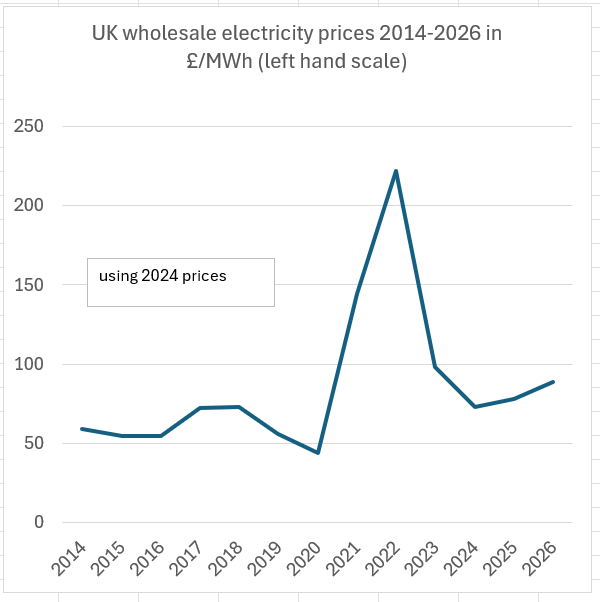
Figure derived using data from Purely Energy
There was hope that a shortage of supplies caused by the loss of Russian gas would be made up by more liquefied natural gas (LNG) supplies, especially from the USA. However, since the height of the Russian gas crisis, gas prices have tended to spike at rather higher prices than was the case before 2020. This is reflected in the wholesale electricity price shown in Figure 2. UK wholesale electricity prices have still been mostly influenced by gas prices
There have been hopes in the gas industry that a global gas glut would develop by 2029, driving down gas prices. Yet, gas gluts can be followed by gas shortages as production waxes and wanes in relation to market prices. Apart from the fact that gluts may be only temporary, few would now bet their houses that the international gas market is free of being seriously affected by geopolitical uncertainties.
It surely must be a highly rational argument that relatively cheap generation prices from solar farms (as well as other renewables) are at least a good hedge against such uncertainty. Indeed, the most realistic medium-term analyses can only suggest that there will be increasing savings for the consumers as the capacity of solar farms increases.
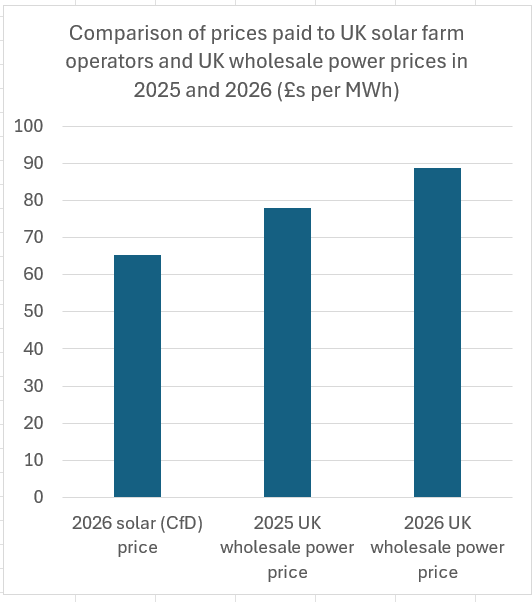
You can see the contrast between CfD prices for solar farms and UK wholesale power prices in Figure 3. Solar farms come in much cheaper at around £65 per MWh. onshore windfarms that have recently been given CfD contracts for £72 per MWh (2024 prices) will also be a lot less than wholesale power prices. The mid-2026 level of wholesale power prices was around £120 per MWh, rather higher than the level of contract prices awarded to offshore wind farms earlier in the year (£91 per MWh).
Figure 3
Sources: Purely Energy and UK Government (using 2024 prices)
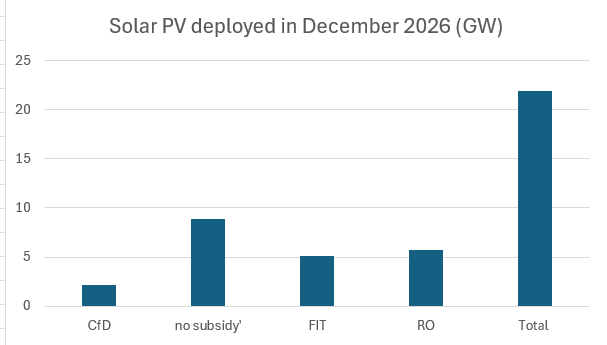
In Figures 4 and 5, I present data from the Modo energy consultancy showing projections on the buildup of solar PV from the different funding streams. Figure 4 shows projected solar PV capacity at the end of 2026 and Figure 5 shows capacity projected at the end of 2030. As can be seen by comparing Figures 4 and 5, the installation of CfD-based solar PV schemes is ramping up.
In the figures, ‘Total’ refers to the total amount of solar PV installed in the UK. The total solar PV installed is expected to rise to over 40 GW by the end of 2030. ‘FIT’ means those schemes that are receiving payments under the ‘feed-in tariff’ scheme, which kick-started small renewables in the UK, and ‘RO’ stands for solar PV projects incentivised by the ‘Renewables Obligation'. FIT ended in 2019, and the RO ended in 2016. As can be seen, there is already over 8 GW of solar PV installed outside of any Government support scheme. The bulk of these are rooftop solar panels.
However (I estimate that) at least 2 GW of solar PV consists of solar farms installed on a ‘merchant’ basis - i.e., outside of any government incentive scheme. The merchant schemes will usually involve supplying solar PV to corporate bodies. Power Purchase Agreements (PPAs) to big ‘creditworthy’ companies will allow the project organisers to raise investment capital to fund the projects. A few community solar projects are also being organised on a ‘merchant’ basis.
Figure 4
Source: Adapted from data published by Modo, see HERE
Figure 5
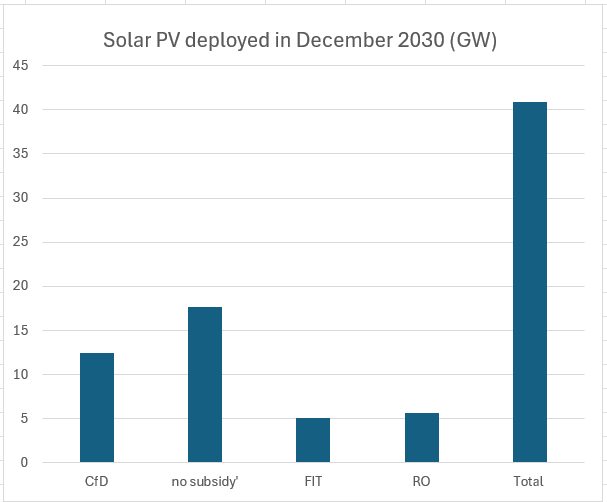
Source: Adapted from data published by Modo, see HERE
All in all, I calculate that by 2031 the UK will be generating around 11 per cent of 2025 levels of its electricity demand from solar PV. Around three-quarters of this will be receiving zero net subsidies from UK consumers (adding up the ‘no subsidy’ and CfD elements of solar PV production). However, the benefits of solar PV production will be, in reality, much larger than appears from these figures. This is because increasingly solar PV will be squeezing the most expensive gas power sources out of the electricity market.
Future of solar PV in the UK
Perhaps the biggest financial benefit of solar PV to the general consumer (that is apart from the individual or commercial customers who install or contract solar PV) will be a general reduction in gas prices. This will occur because, according to Modo consultancy, by 2035 solar PV will be the ‘marginal’ electricity producer on 80 of the (summer) days a year (See HERE). Much expensive gas production will be replaced by much cheaper solar production selling at close to nothing.
Indeed, prices will often be negative. In these circumstances, rather than simply switching off production, solar farms will sell their power to either their own or a different utility-scale battery. This power will then be sold onto the grid in the evening, undercutting and thus displacing a lot of expensive gas power production that currently has to be used.
I have not seen any projections quantifying the future reductions in the wholesale power price caused by these effects, but they will be large.
Reducing wholesale power and other costs
The Energy and Climate Intelligence Unit (ECIU) has calculated that wind power alone has reduced wholesale power costs by around £24 per MWh (See HERE). This number will increase as more wind and solar PV become grid-connected. The value in reducing gas costs will increase over the next few years as there is a reduction in the amount of time gas power forms the marginal price in the electricity trading system.
Counter to this, some have argued that solar PV ought also to pay for the provision of capacity since solar PV fluctuates. Yet this is a vacuous argument. The solar-critics argue that without solar the system would still need the same amount of capacity. But by logic, therefore, putting solar PV on the system does not add extra costs to the system! In fact, far from being a cost to the system, solar PV is actually penalised.
Solar PV is penalised because existing fossil fuel and nuclear power plants obtain subsidies for providing capacity through the ‘capacity mechanism’ organised by the National Electricity System Operator (NESO). Besides all this, of course, battery storage (which provides system capacity) is increasingly being associated with solar farms. This is either directly through co-location or indirectly through so-called ‘hybrid’ contracts. So in fact, because solar PV encourages batteries to be built, it is actually reducing the costs of providing electricity to the system. Solar farms pay for their own grid connections as well. Far from adding to capacity costs, it is actually reducing them.
Conclusion
I have focused here on how increasing solar PV reduces costs for the consumer. Of course, the greatest gain in the policy is that carbon emissions are cut and the climate impact of electricity is reduced. Solar PV is now the most cost-effective means of not only cutting consumer bills but also the quickest way to reduce carbon emissions.
Of course, solar PV on its own cannot solve all our problems. We need lots of wind power too! That having been said, I have argued in a different post that ‘Even in not-always-sunny UK, solar PV could provide up to 40 per cent of annual electricity production. That is without a significant amount of curtailment of production or even the need to convert the electricity into stored energy such as hydrogen. Of course, this is dependent on there being enough provision of batteries.’ See HERE
We shall still need the majority of electricity supply from other sources. Wind power will be the leader here, especially as it complements solar PV. Wind power generation has the highest volume in winter, whilst there is much more solar PV production in the summer than in winter.
Come to the Conference on solar power planning on Wednesday, September 9th in London! Organised by the University of Aberdeen in report back on an ESRC research project
Hear from, and join in the discussion with, industry leaders, academics and others about ground-mounted solar PV. Speakers include Dan Meredith, Director of External Affairs, Solar Energy UK, Owen Pike, Eden Renewables, Rebecca Windemer, REGEN, Doug Parr, Chief Scientist – Greenpeace and others. For details, see the link HERE
We now need to gets these facts out to the general population, in terms that Deform UK Ltd and their followers can understand.
In Q2 Solar CfDs returned 7.7m in the same qtr Offshore wind gained back 372m despite the average system price being high through the quarter. Granted solar CfD contract actualisation is coming on fast unlike its wind brethren who are hanging out to their long stop date so the gap will close up but wind will still be a nett recipient till well into the 2030s and if Hormuz gets sorted out the costs will only go one way.
Also i agree it does lower wholesale price but thats no longer representative of the true cost of the energy to consumers as the various subsidy regimes then have to be added back in by the time it gets to your meter. Also this distortion of the wholesale price is benefiting battery operators unfairly and even worse we end up giving energy away to any trader who has access to capacity on an interconnector.
then we also have NESO/DESNZ telling us there's still too many BESS proposals in the connection queue!! We need more as that will stop the stupid negative pricing we are seeing but as usual even Labour succumbs to letting corporations dictate policy.
Thus there is lot that still needs sorting out in the energy market yet REMA drags on and on.